
The future of financial support is digital-first, but not human-free
Consumers across Europe are embracing AI in all facets of their lives. As they build their understanding of what the technology can and cannot do, they start to integrate specific tools into their routines to perform boring tasks and take care of life admin. The use of AI in personal finances is a perfect example of how quickly this is happening.
Highlights of the article
- AI use for personal finances has doubled since 2025. Germany rank highest in Europe.
- AI can make financial support more accessible, especially for consumers who find money matters difficult to navigate.
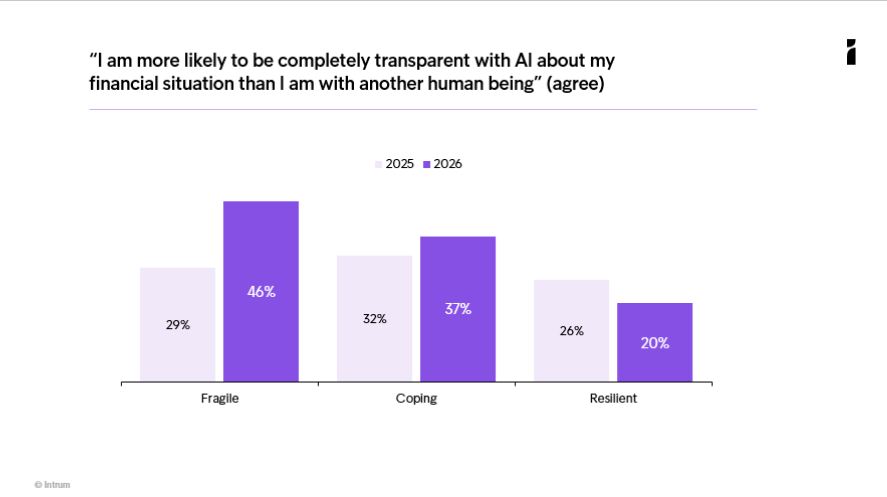
- Fragile consumers are more willing to open up to AI, but still want the option of human support. 46% say they would be more transparent about their finances with AI than with a person.
- For businesses, AI could improve payment discipline while reducing the cost of managing late payments by up to 20%.
- The future is hybrid: combining digital efficiency with human empathy can benefit both consumers and businesses.
In this year’s European Consumer Payment Report (ECPR), we see a clear rise in the number of consumers becoming money-management ‘centaurs’, in that they are combining their own judgment with AI tools to better organise their personal finances.
Compared to last year, more than twice as many Europeans have started using AI to manage their finances (from 13 per cent to 29 per cent), with the proportion approaching half in Germany and the UK where general AI use is also notably high.
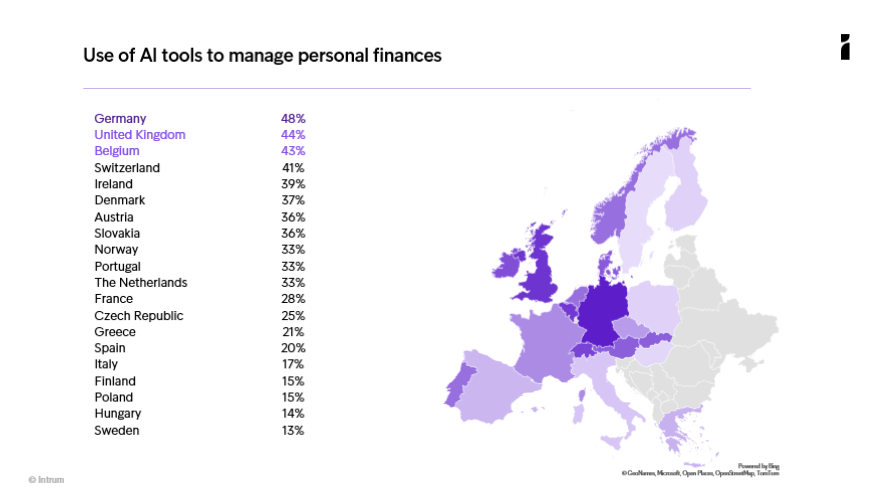
We also see a reduction in the proportion of consumers who are nervous about sharing their personal information with AI, from 50 per cent to 42 per cent, reflecting greater overall trust in the technology and regulation, with confidence particularly high among women and Gen Z respondents.
AI may support greater payment discipline
Consumer-facing businesses expect the public’s adoption of AI tools in payment management will guarantee them more reliable revenue streams.
Businesses are benefitting from back-office efficiencies
In our 2026 European Payment Report, based on data from close to 10,000 executives in 20 countries, about half of B2C leaders (48 per cent) anticipated customers getting better at making payments on time now that they had AI to help them plan. These businesses are also benefitting from back-office efficiencies enabled by the technology to the extent that implementing AI could, according to our calculations, help them cut the labour costs of chasing late payments by about 20 per cent.
As such, businesses have a strong incentive to develop and encourage the use of consumer-facing AI tools and platforms, whether these are specialised chatbots to make it easier for customers to discuss payment plans or domain-specific explainer tools to help them understand complex financial products.
At the start of 2026, half of B2C leaders (48 per cent) anticipated customers getting better at making payments on time now that they had AI to help them plan.Insights from Intrum EPR 2026 based on data from close to 10,000 executives in Europe
A new way to help the consumers who are struggling the most
Businesses also face a bigger, more ambitious opportunity. As a recent report by the UK government argues, AI can help address deep-seated weaknesses in the broader financial system. It could potentially help bridge the ‘advice gap’ whereby just 9 per cent of consumers seek traditional financial advice. It could also support general financial literacy by providing clear breakdowns of financial terms and conditions, helping consumers make better-informed financial decisions. AI therefore gives B2C companies a new way to help the consumers who are struggling the most.
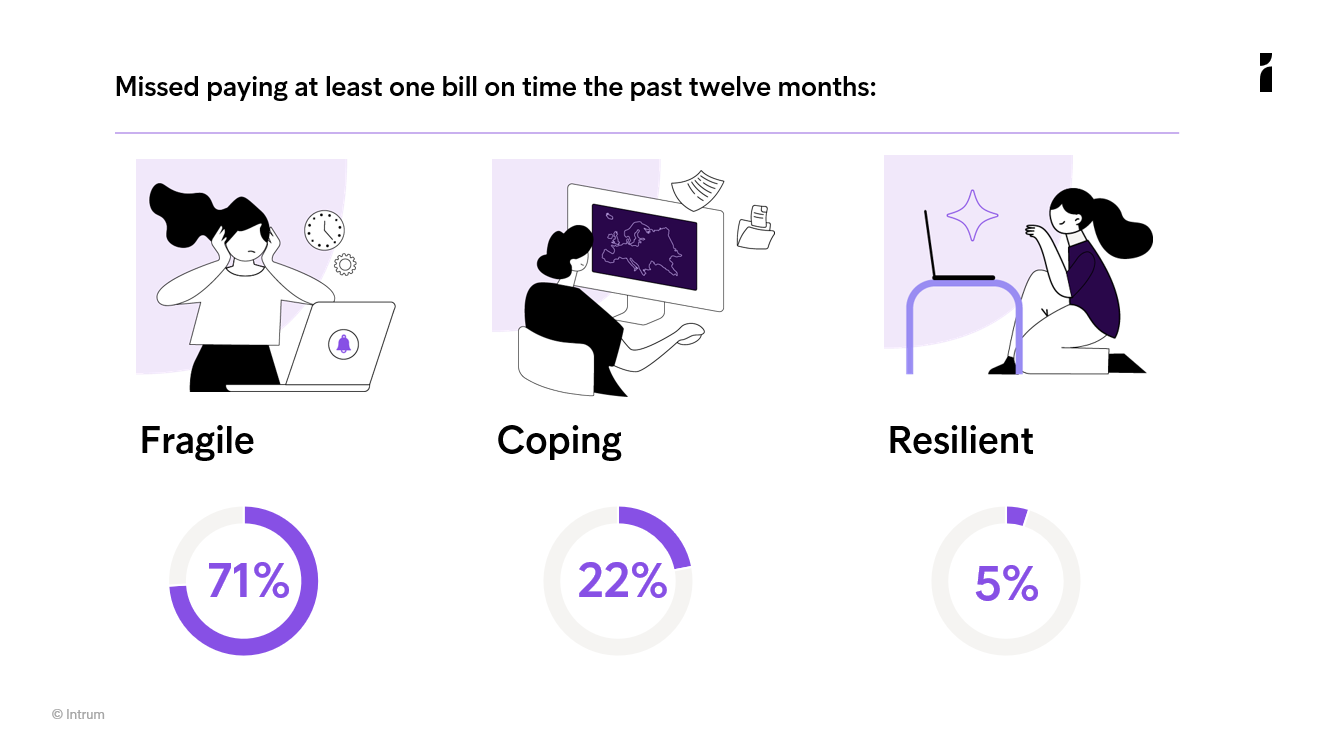
Money Management Index: 7 in 10 financially fragile consumers have paid late
Among the ‘fragile’ group in Intrum’s Money Management Index, 71 per cent have missed at least one payment in the last 12 months, compared with 22 per cent of the ‘coping’ group and 5 per cent of the ‘resilient’ group.
Helping these consumers manage their finances more effectively could help millions of people achieve greater financial stability and personal wellbeing, while also protecting future revenues by reducing the overall number of people likely to default.
To realise this opportunity, B2C executives need to understand consumers’ AI-related preferences and behaviours, and what might be preventing those in the fragile group from using the technology more than they are.
Hybrid interaction: keeping the human in the loop
In this year’s ECPR, we find some apparent contradictions that, on closer inspection, actually tell a nuanced story about how consumers are engaging with companies via chatbots and other interfaces. By recognising these nuances, businesses will find it easier to encourage greater use of the tools.
On one level, consumers – and particularly those who fall into the fragile category – show a growing openness to engaging with AI agents. About half of fragile consumers (46 per cent) say they are more likely to be completely transparent with AI about their financial situations than with another human, compared with 37 per cent of coping consumers and 20 per cent of resilient consumers.
Clear preference among consumers to be able to talk to a human
But we also see a very clear preference among consumers to be able to talk to a human if need be. Almost two in three people in the fragile group (63 per cent), and 56 per cent of consumers on average, say they would trust AI more if they could speak with a human adviser on request.
This disconnect, of showing trust in AI on one hand while reserving the right to talk to a real person on the other, may be based on a preconception that AI cannot be sympathetic to the complex, emotional reasons behind debt, such as those relating to human relationships or to managing unexpected domestic or employment situations. Almost half of fragile consumers (47 per cent) say they are uncomfortable with AI making financial decisions because it may not understand their personal circumstances.
The takeaway
The takeaway is that fragile consumers are wary of humans if they think they might be judged for struggling financially or making poor choices. At the same time, the financially fragile group want the option to talk to a person if they are experiencing life challenges that another human might understand.
B2C businesses should therefore consider a hybrid mix of humans and bots, anticipating when and why consumers might want to use one channel over another. In ECPR last year, we explained how they could think about specific types of consumers, each with different preferences.
Those in the ‘financially strained and job-anxious’ category may respond best to AI-powered ‘entry points’ with the option to escalate to a human, whereas consumers in the ‘self-disciplined optimiser’ category will favour very little interaction, much of it digital-first.
Widespread need for clearer guidance
One of the most important routes to financial security is financial literacy. This has repeatedly shown up in our ECPR data.
In this year’s report, fragile consumers are much less likely to say that their parents gave them a good financial understanding (28 per cent vs 45 per cent of consumers on average). These individuals are also more likely to find financial terminology to be confusing and stressful (38 per cent vs 17 per cent of consumers on average).
This is one area where the greater use of AI tools could prove to be extremely helpful. Although caution should be exercised with any information that is provided by LLMs, AI technology can provide clearly written and understandable summaries of technical information.
Too trusting in the past and are now overly cautious?
Fragile consumers are, however, less than half as likely as those in other groups to turn to ChatGPT, Claude and other tools to help them understand and navigate their financial situation. In another data point, just one in three (34%) frequently uses commonly available AI tools to help them understand financial terms and conditions, even though they acknowledge they lack knowledge in this area. This compares with 41 per cent of coping consumers.
One explanation for fragile consumers’ reluctance here could be that they have been too trusting in the past and are now overly cautious. About one in four consumers say, for example, that taking financial guidance from influencers on social media has made their financial situation worse, which is higher than in the other groups.
In response, B2C businesses that are creating customer-facing ‘explainer’ AI tools will need to take extra steps to nurture trust among consumers. As well as making a human available if needed, as mentioned above, they could make it very clear that the tool is based on proprietary data and has been vetted by industry specialists.
About one in four financially fragile consumers say, for example, that taking financial guidance from influencers on social media has made their financial situation worse, which is higher than in the other groups.Insights from Intrum European Consumer Payment Report 2026, based on 20,000 consumers in 20 markets
The next frontier
AI is evolving so quickly that it’s impossible to provide a comprehensive guide for its use by B2C companies. In this article, we have primarily been describing LLM-based interfaces and summation tools, but these are already less sophisticated than the coming generation of autonomous and semi-autonomous AI agents.
Transformative for consumer payment management
The potential for agents is similarly transformative for consumer payment management. Fragile consumers are, for example, twice as likely as the average European consumer to say they get into debt without realising they are doing so. Here is an area where an agent-supported solution could provide greater, more proactive visibility of upcoming commitments. For coping and resilient consumers, it would help them get even better at managing their money.
Ultimately, the opportunity presented by AI extends beyond efficiency and timely payments. If companies can balance AI’s computing power with human empathy, they can help consumers make better financial decisions, creating a generation of responsible, reliable money-management centaurs.

